City, county continue gravel tax debate
TONY BROWN/DAILY FORUM
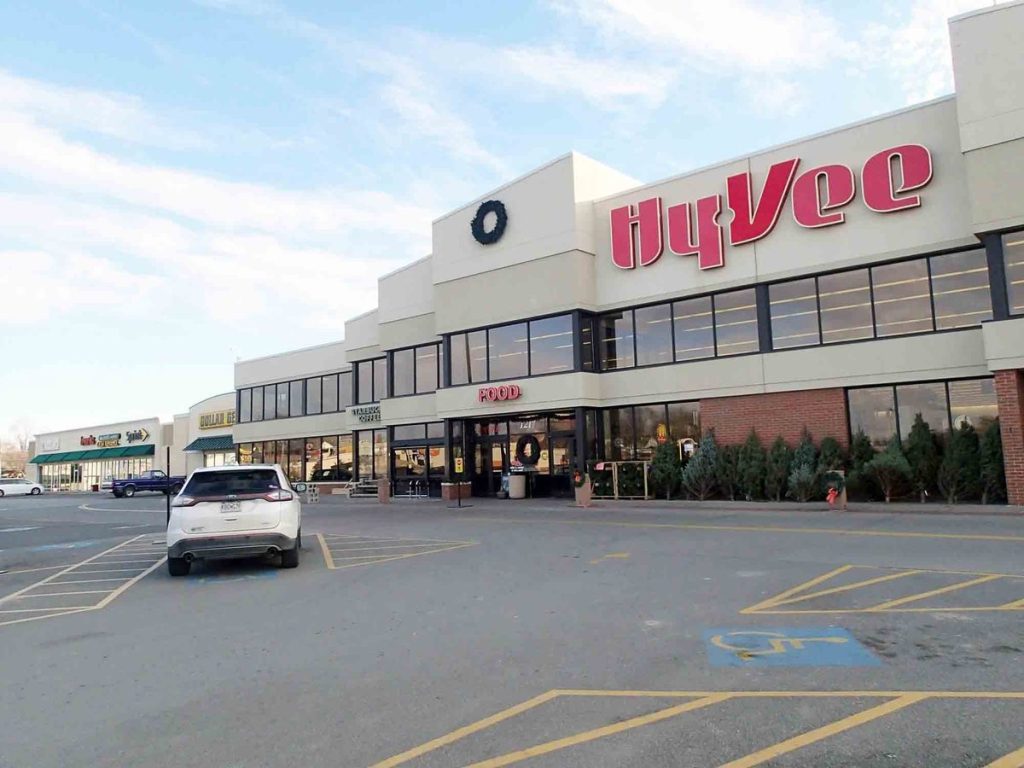
The Town Center retail complex TIF district, anchored by the local Hy-Vee supermarket, continues to be a source of conflict between the City of Maryville and the Nodaway County Commission, which has refused to contribute a portion of road gravel sales tax revenues for the repayment of TIF-related municipal debt. City Manager Greg McDanel, supported by the city’s legal counsel, Gilmore & Bell, is insisting that the money is owed under state law.
Maryville City Manager Greg McDanel was to meet with Nodaway County Commission again today (Wednesday, Dec. 14) in an attempt to convince the county to reconsider its refusal to divert a portion of a half-cent sales tax earmarked for road gravel to debt service related to the Town Center tax increment financing district.
The city is claiming that handing over about $30,000 a year from the tax’s nearly $1 million in revenue is a requirement under state law, which allows cities to recoup a portion of local sales taxes imposed on retail transactions within TIF districts — tax abatement zones created for the purpose of redeveloping blighted areas.
In the case of the Town Center TIF, the city borrowed $2.5 million in 2005 to pay for infrastructure improvements associated with the retail complex anchored by the Hy-Vee supermarket.
McDanel said following this week’s City Council meeting that the additional county revenues would benefit all local taxing entities, including Nodaway County, the city, and Maryville R-II schools, by returning Town Center to the “active tax rolls.”
TIFs work by freezing property taxes in blighted areas at a pre-development level and allowing cities to borrow against the “tax increment,” that is the difference between the district’s “blighted” assessment and its enhanced valuation once redevelopment work is carried out and the debt paid off.
McDanel said it is in the city’s and county’s best interest to pay off the TIF debt as soon as possible, since depreciation could lower the property’s assessed value as time goes on.
A fraction of the revenue from two half-cent sales taxes used to fund general county government operations has been diverted toward TIF debt service from the beginning, and the city’s position is that the gravel tax is no exception.
However, in an apparent oversight, the city neglected to ask for its share of the tax after it went into effect two years ago. McDanel said that as “a positive gesture” the city was not seeking revenue already collected but only a share of receipts coming in after Jan. 1, 2017.
He added that the city’s appeal is not a request but a requirement under state law supported by counsel from Gilmore & Bell, a large law firm specializing in municipal government retained by the city.
The three-member County Commission disagrees.
After meeting with McDanel Nov. 30, the commission on Friday, during a consultation with Prosecuting Attorney Robert Rice, declared it would not hand over any gravel tax revenue, at least until it can be proven that it is required to do so.
While under the original state statute, the city would appear to have a strong argument, the Missouri Legislature complicated the matter by passing an exception to the TIF formula that exempted “economic activity” sales taxes as of August 2014.
Voters approved the gravel tax in April 2014, prior to the exemption. However the tax was not implemented until Oct. 2014, which the commissioners believe means they may not have to pay.
The governing board also counters that a county ordinance implementing the gravel tax specifies that all revenue so derived must be spent solely on county- and township-owned transportation infrastructure.
On Monday, McDanel repeated his argument that ordinances passed by the commission are superseded by state law.
If the commission persists in its decision not to hand over a portion of gravel tax revenues, the city could file a lawsuit. McDanel has said, however, that taking the matter to court could cost taxpayers more than would be gained by reducing the term of remaining TIF debt.
Originally scheduled to end in 2025, the city’s TIF obligation was refinanced in 2015 for $1.7 million, which municipal Finance Director Denise Town said should shorten the term of repayment by a year or so.